Access the Capital Your Business Needs.

The right financing at the right time can accelerate growth, stabilize operations, or open doors that would otherwise stay closed. We help businesses identify, prepare for, and access the loan products that fit their situation.
Capital Solutions

Financing That Fits Where Your Business Is Going.

Business financing isn’t one-size-fits-all. The right loan product depends on what you’re trying to accomplish, how your business is positioned, and what lenders will see when they review your application.
We help businesses navigate the landscape — matching them to the loan types that fit their situation, preparing their financials and documentation, and guiding the application process through to closing.
Loan Types Covered

6 Categories

SBA, term, line of credit, equipment, bridge, and working capital financing options.
Our Role

Advisory

We help you identify, prepare for, and pursue the right financing — not originate or broker it.

We Prepare You Before You Apply

The difference between an approval and a decline often comes down to how prepared the business is — not just whether it qualifies on paper. We help businesses understand what lenders look for, organize their financial documentation, and position their application in the strongest way before it goes out.

Matching Loan Type to Business Purpose

Different loan types serve different purposes — and using the wrong product for a given need can mean unnecessarily high costs, mismatched terms, or financing that creates problems later. We help businesses match the right product to the right use before they pursue it.

Understanding the Full Cost of Capital

Interest rate is only one component of borrowing costs. Term length, origination fees, prepayment penalties, collateral requirements, and personal guarantee provisions all shape the true cost and risk profile of a loan. We help clients evaluate the full picture, not just the headline rate.
Loan Types

Six Categories of Business Financing

Each loan type has different terms, requirements, use cases, and trade-offs. Understanding the landscape helps businesses pursue the right financing — not just the most accessible one.
Lender Considerations

What Lenders Look at — and
How to Be Prepared

Understanding what lenders evaluate helps businesses prepare proactively — addressing gaps before they become reasons for a decline, and entering the process in a stronger position.
Factors That Strengthen an Application

Consistent, documented revenue

Lenders want to see stable or growing revenue over time — not just a strong recent month. Bank statements and financial statements that tell a consistent story carry significant weight.

Strong business and personal credit

Both scores matter, particularly for small businesses. A clean credit history without significant derogatory marks reduces perceived risk and can improve the terms offered.

Clear purpose and repayment plan

Being able to articulate clearly what the funds will be used for and how the business will service the debt shows lenders the loan is tied to a defined business outcome.

Time in business

Most lenders want to see a track record. Longer time in business reduces perceived risk — especially for SBA and traditional bank products. Two or more years is a common threshold.

Clean, organized financial documentation

Lenders review financial statements, tax returns, bank statements, and in some cases projections. Having these organized and consistent with each other signals a well-managed business.

Common Friction Points to Address in Advance

Inconsistent or undocumented revenue

Revenue that doesn’t match what appears in bank statements, or that isn’t supported by clear records, creates gaps that slow underwriting or lead to declines.

Outstanding liens or judgments

Tax liens, UCC filings from prior lenders, or unresolved legal judgments show up in lender reviews and can block approval until addressed.

Mixing personal and business finances

Businesses that haven’t maintained a clean separation between personal and business accounts create underwriting complexity — and raise questions about the reliability of the financial picture presented.

High existing debt-to-income ratios

Significant existing debt obligations reduce available cash flow for new debt service. Lenders calculate this ratio carefully — and a business that’s already heavily leveraged faces higher scrutiny.

Pursuing the wrong product for the use case

Applying for a loan type that doesn’t fit the purpose — too short, too long, wrong structure — can result in declining or terms that don’t serve the business well even when approved.

Our Process

How We Guide the Financing Journey

Business financing advisory follows a structured path — beginning with understanding your situation and ending with a business positioned to pursue the right capital through the right channels.
01

Situation Assessment

Understanding what you’re trying to accomplish, what the business looks like on paper, and what financing options are realistically in range given your current position. This determines where to focus before anything goes to a lender.
Business Review
Financial Overview
Goal Clarification
02

Loan Type Matching

Identifying which financing products fit the purpose, the business profile, and the timeline. We narrow the field to the products that are genuinely appropriate — not everything that exists, but the options that make sense for this specific situation.
Product Analysis
Lender Landscape
Term Modeling
03

Financial Preparation

Organizing and reviewing the financial documentation lenders will request — statements, returns, bank records, business documentation — and identifying anything that needs to be addressed, explained, or corrected before the application goes out.
Document Review
Gap Identification
Record Organization
04

Application Positioning

Helping present the business in the most accurate, complete, and favorable way possible — not by misrepresenting anything, but by ensuring the full story of the business is clearly communicated in the documentation lenders will see.
Narrative Clarity
Package Review
Submission Prep
05

Lender Coordination Support

Supporting the business through the lender review process — responding to requests for additional documentation, helping interpret term sheets and conditions, and ensuring the business can evaluate the terms offered with a full understanding of what they mean.
Process Navigation
Term Review
Closing Support
Get Started

Find Out What Financing Options Are Right for Your Business.

The right place to start is a conversation. We’ll help you understand where your business stands, what options are realistically in range, and what preparation looks like before you approach a lender.

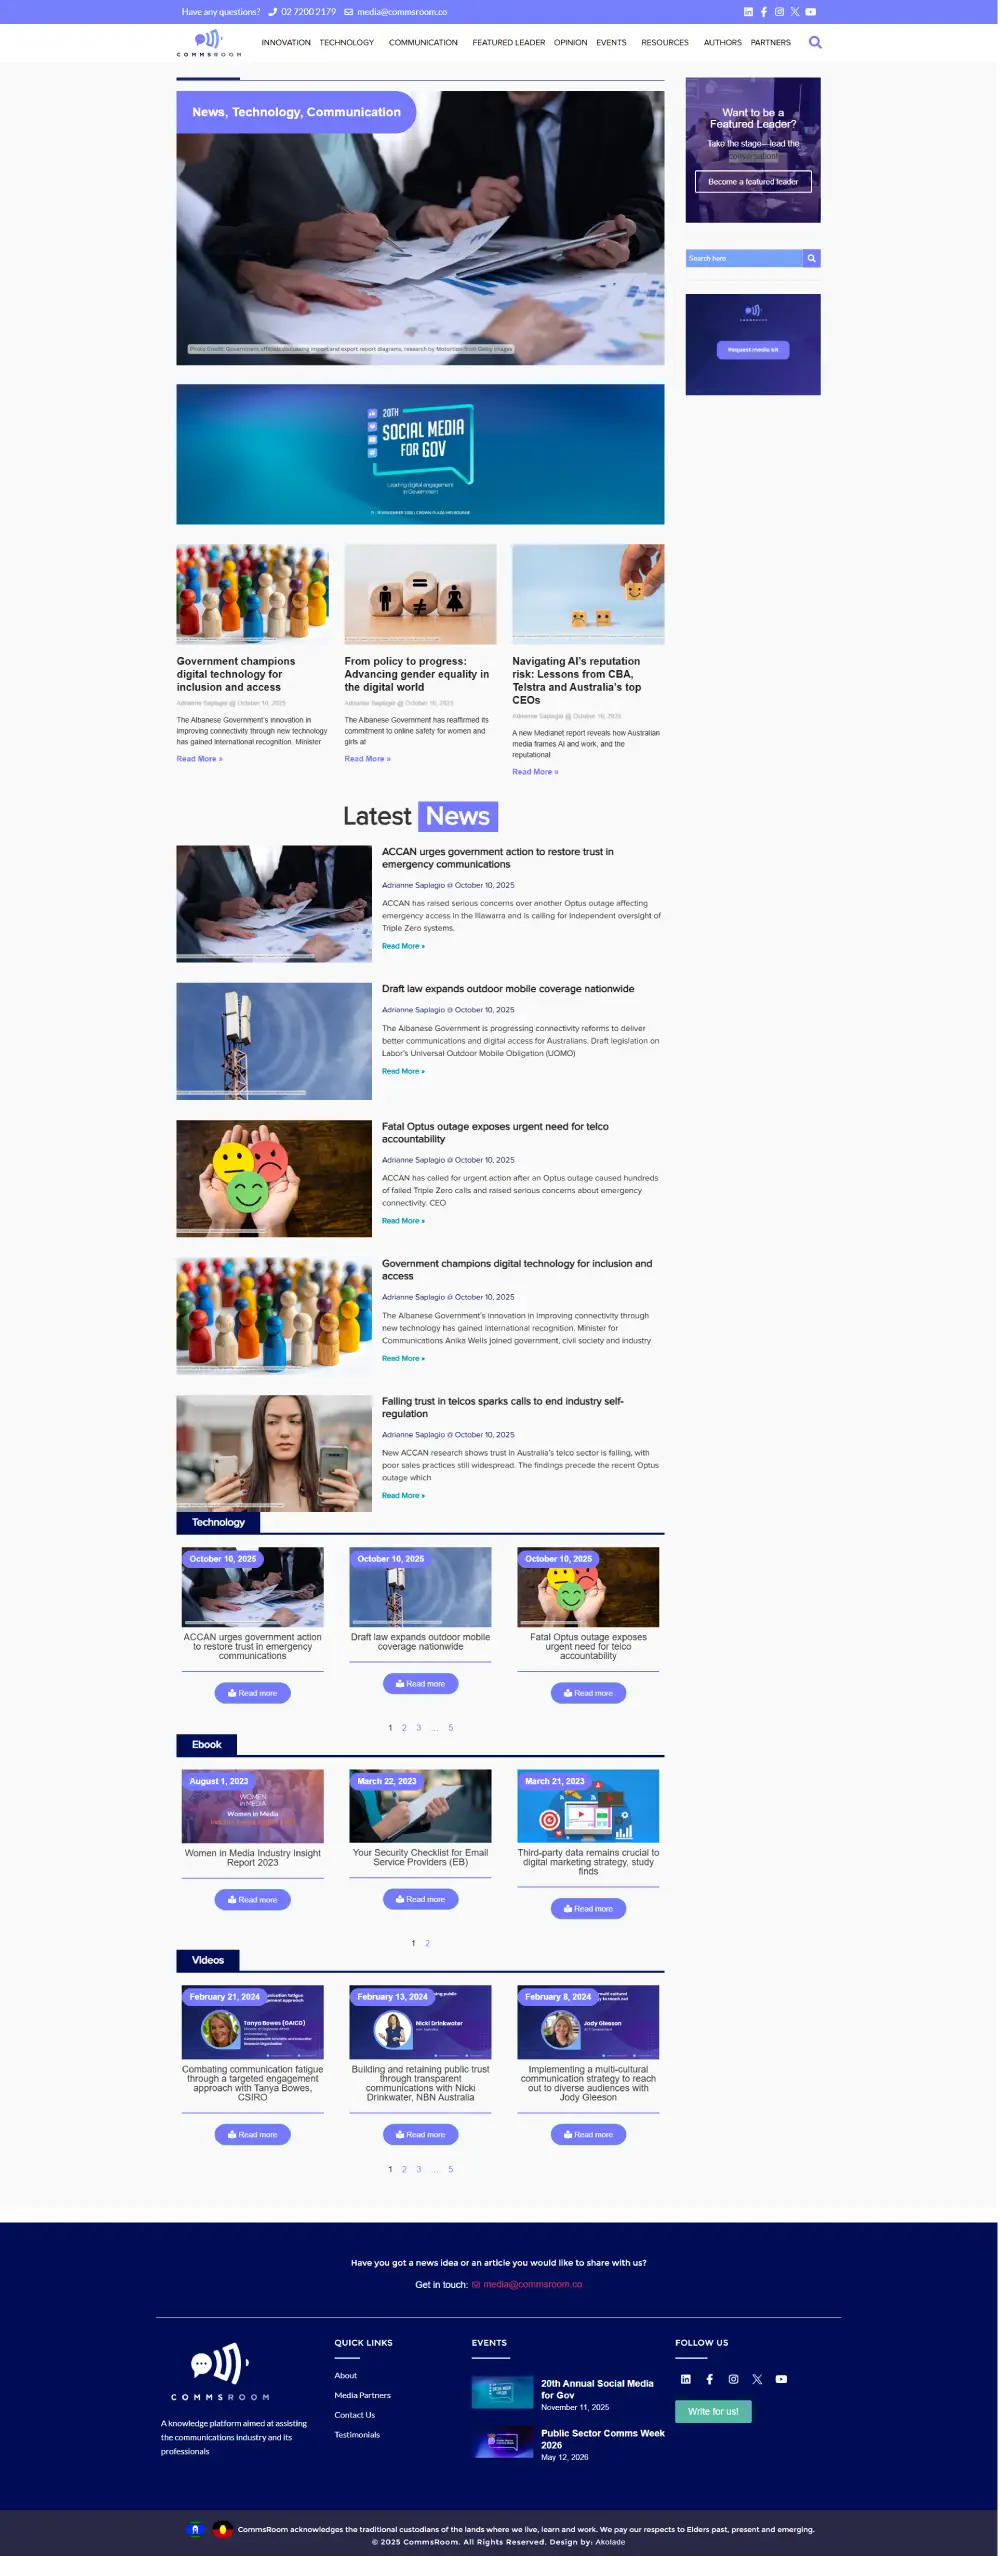
Transforming News Publishing With Dynamic Functionality

Comms Room, a leading communications newsletter website, wanted a modernized platform with a custom post type (CPT) setup to manage their daily articles and categorized content efficiently.

We developed a fully dynamic, user-friendly website that automates content organization, enhances navigation between topics, and supports high-volume publishing. The result is a sleek, modern platform that streamlines content management while elevating the reader experience — keeping Comms Room’s news delivery fast, engaging, and future-ready.