Construction financing requires more than capital. It requires a lender-ready project, structured draw management, and a clear path from groundbreaking through certificate of occupancy. We help builders and developers navigate every phase.
A construction loan is not a mortgage. It is short-term, draw-based financing that funds a project in phases as work is completed and verified. Understanding how this financing structure works — and what lenders require at each stage — is fundamental to accessing it successfully.
We work with builders, developers, and investors undertaking construction projects to ensure they approach the financing process correctly: with the right loan type, lender-ready documentation, and a clear project plan that supports the draw schedule they will need to manage.
Construction loans are typically structured for 6–18 months, covering the build period. Once construction is complete, the loan is either repaid, refinanced, or — with a construction-to-permanent product — converts to long-term financing.
Funds are not released in a lump sum. They are disbursed in draws — tied to verified project milestones — which is why proper budgeting, documentation, and inspections matter from day one.
Lenders want to see the project plan, contractor credentials, cost breakdowns, permits, and land valuation — often before the first dollar is committed. Being lender-ready before approaching financing is essential.
Most construction loans accrue interest only on funds drawn during the build period — not the full loan amount — which reduces carrying costs while the project is underway.
Construction funds are released in draws tied to verified project progress. Understanding the typical draw structure helps builders plan their cash flow and ensures they can meet the documentation requirements at each phase.
Land clearing, grading, utilities rough-in, foundation pour, and footing completion. The first draw is typically released after land cost is confirmed and permits are secured — often including a portion held in reserve.
Wall framing, roof structure, sheathing, and structural systems. This phase establishes the physical form of the building and is typically verified by lender inspection before the draw is released.
HVAC, electrical wiring, and plumbing rough-in before walls are closed. This is often the largest single cost phase on a custom build and requires clean inspection sign-offs before the draw is processed.
Drywall, flooring, cabinetry, trim, fixtures, and interior completion. The project begins to take visible shape in this phase. Budget tracking becomes critical here as change orders are most common.
Final punch list work, landscaping, final inspections, and certificate of occupancy. The final draw — sometimes 5–10% held in retention — is released after the project is fully complete and all inspections are passed.
Different projects require different financing structures. We help clients identify the product that fits their specific build type, timeline, and exit strategy.
Short-term financing for building a new structure from scratch on vacant land or a cleared site. Covers land, site prep, and full construction costs through to completion, with disbursements tied to construction milestones and lender inspections.
A single loan that covers both the construction phase and automatically converts to a permanent mortgage upon project completion. Reduces closing costs and simplifies the financing process by eliminating the need to separately secure permanent financing after the build.
A revolving construction line of credit for builders who construct homes on speculation — building without a pre-committed buyer. Allows draws for multiple projects simultaneously and is structured around the builder’s overall project pipeline rather than a single build.
Financing for substantial renovation or rehabilitation of an existing property — covering both acquisition (if applicable) and renovation costs. Draws are released against verified work completion, and the after-renovation value (ARV) plays a key role in loan sizing.
Financing for the construction of commercial properties — office, retail, industrial, mixed-use, or multi-family. Underwritten on the projected NOI of the completed property or the creditworthiness of the borrower and project. Typically larger and more complex than residential construction financing.
Understanding the mechanics — and the common failure points — is what separates projects that close and build cleanly from those that stall, over-budget, or fail to draw.
Lenders are not just evaluating the borrower — they are evaluating the project itself: the plans, the contractor, the budget, the timeline, and the feasibility of completing on-spec and on-budget. Weak project documentation is one of the most common reasons construction loans are delayed or declined.
Construction projects don’t spend evenly. Costs cluster at specific phases, draws require lead time, and inspections create delays. Builders who don’t plan their cash flow carefully — factoring in draw timing, retainage, and contractor payment schedules — often find themselves cash-constrained mid-project.
Construction loans are sized against a budget. When costs exceed that budget — through change orders, material price increases, or unforeseen conditions — there is no automatic additional funding. The builder must have a contingency plan and reserves. We help clients plan for this before it becomes a problem.
Construction lenders evaluate both the borrower and the project. Arriving at a lender conversation well-prepared — with the right documentation and a clear project plan — is what separates a clean approval from a frustrating process.

Stamped architectural plans, engineering drawings, and permit documentation give the lender confidence the project is properly designed and legally approved to proceed.
A line-by-line construction budget that accounts for all phases — including a contingency reserve — shows the lender the project is financially thought-through and appropriately sized.
Lenders want to see that a licensed, bonded general contractor is engaged. GC license, insurance certificates, and a signed construction contract are typically required.
The land being built on must be owned or under contract. Land equity can often serve as part of the down payment contribution required by the lender.
Credit history, liquid reserves, net worth, and prior construction or real estate experience all factor into the lender's evaluation — particularly for larger or more complex projects.
The lender wants to understand how the loan will be repaid at the end of the construction term — through sale of the property, refinance to permanent financing, or conversion (for construction-to-permanent products).

Financing for commercial real estate acquisitions, owner-occupied properties, and commercial mortgage refinancing.

DSCR loans, portfolio financing, and investment property strategies for real estate investors building rental portfolios.
Entity selection, formation filing, and operating documentation — the right structure before you pursue financing.
Construction financing is complex. Start with a conversation — we’ll help you understand what lenders will need, what the process looks like, and what you need to have in place before you approach financing.
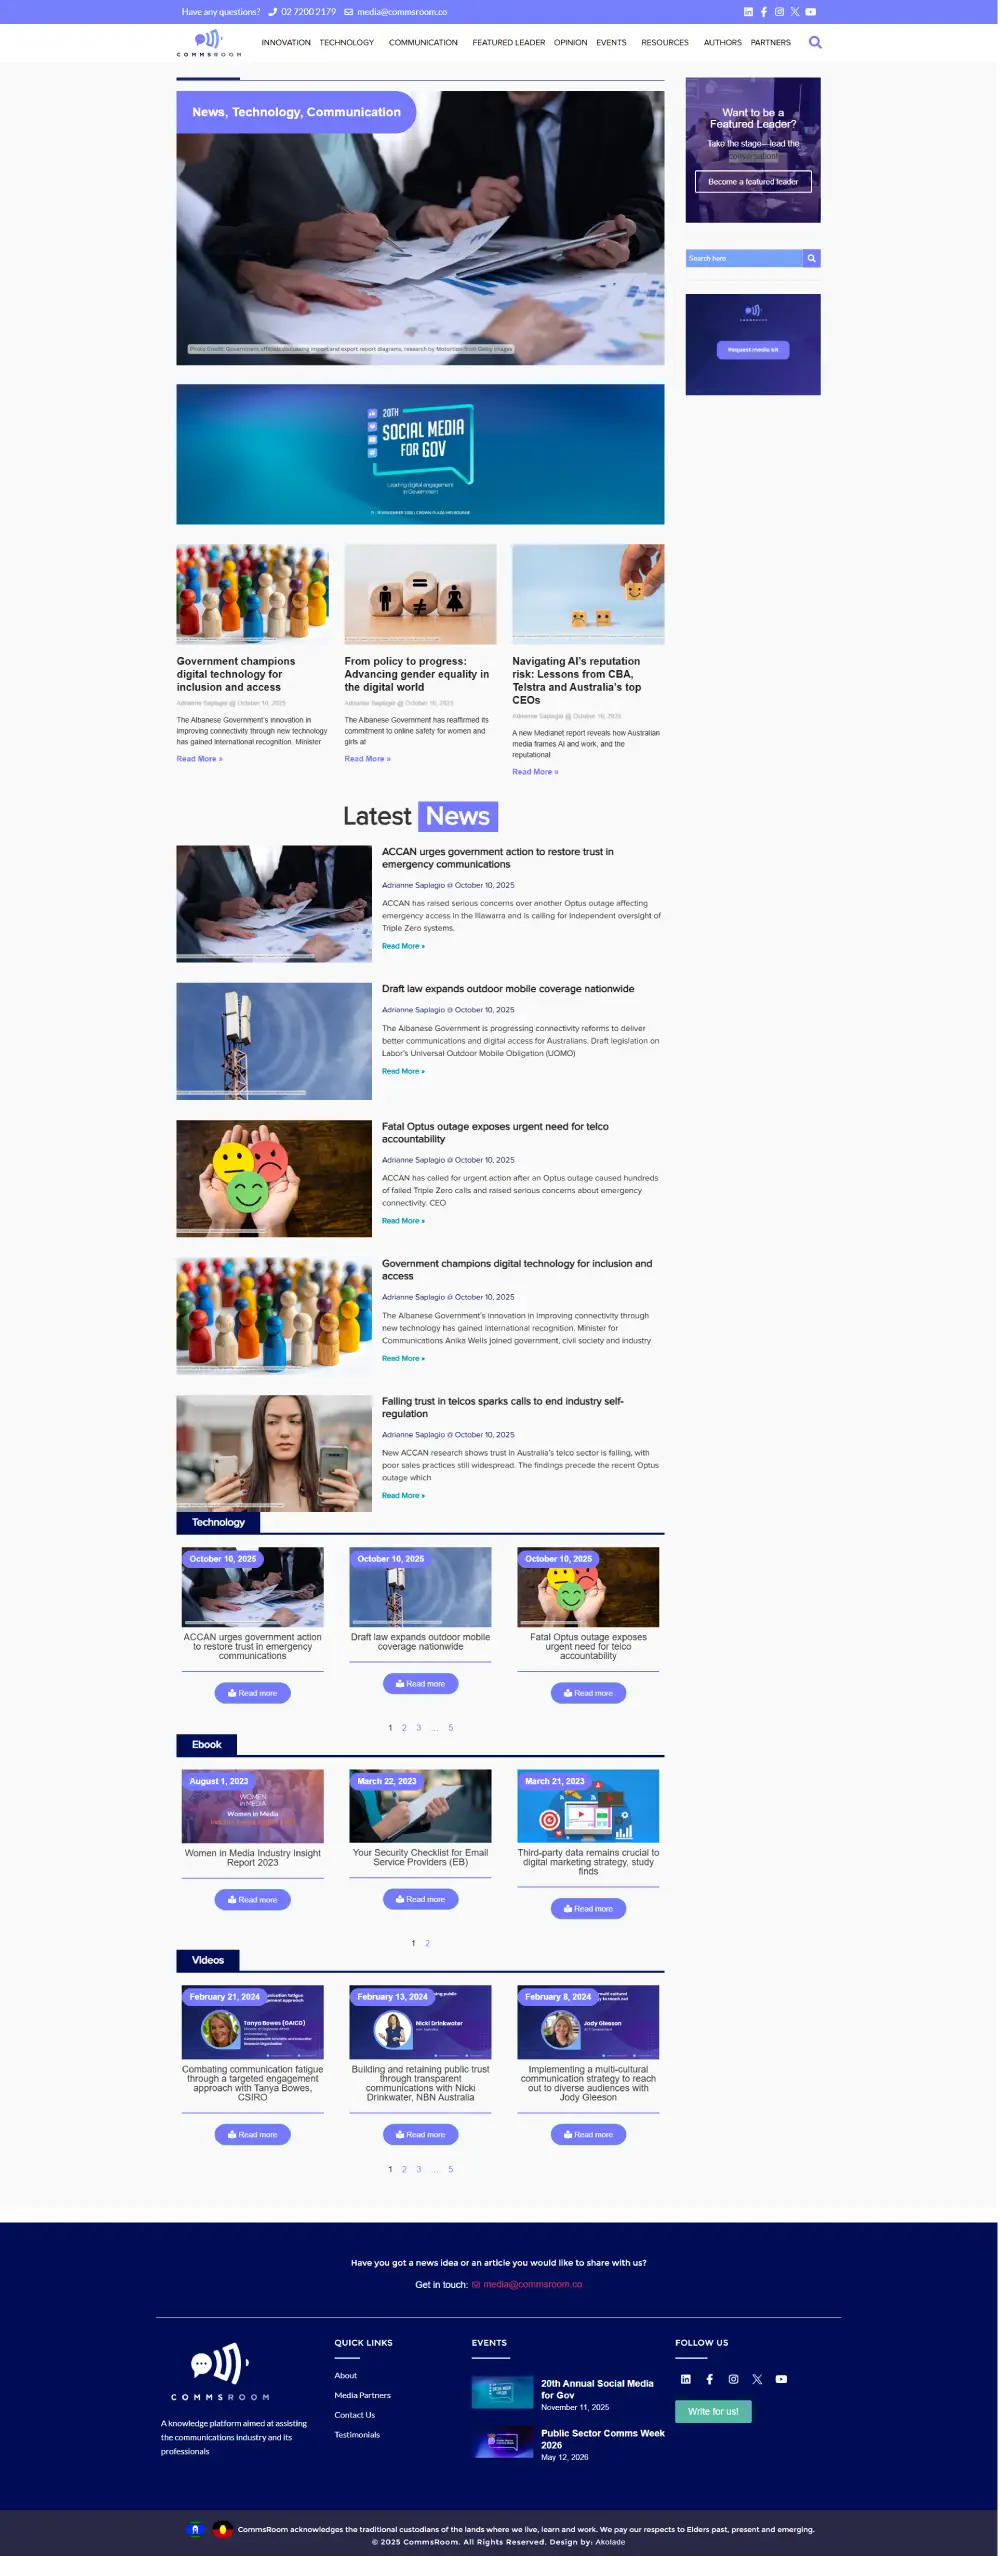
Comms Room, a leading communications newsletter website, wanted a modernized platform with a custom post type (CPT) setup to manage their daily articles and categorized content efficiently.
We developed a fully dynamic, user-friendly website that automates content organization, enhances navigation between topics, and supports high-volume publishing. The result is a sleek, modern platform that streamlines content management while elevating the reader experience — keeping Comms Room’s news delivery fast, engaging, and future-ready.