From owner-occupied commercial mortgages to investment property acquisition and commercial refinancing — we help business owners and investors understand what lenders need and how to position their transaction for approval.
Preparing the documentation and financial package lenders require before you approach the process.
Understanding which loan program and which lender type are the right match for your specific transaction.
Reviewing the terms, provisions, and long-term implications of the commitment before you sign.
Identifying the ownership structure and entity approach that supports the financing strategy.
Commercial real estate loans cover a broad range of property types, borrower profiles, and financing purposes — from a business owner buying the building they operate out of, to an investor acquiring a multi-tenant retail center. The right loan product, lender type, and structuring approach depend heavily on those specific variables.
We work with business owners and commercial real estate investors to clarify which financing options are appropriate for their transaction, what lenders will evaluate, and how to approach the process in a way that supports a clean, efficient outcome.
Commercial financing applies to retail, office, industrial, mixed-use, hospitality, self-storage, medical, and multi-family (5+ units). Each property class carries different underwriting considerations and lender appetite.
Commercial loans are typically underwritten on the property's income-generating capacity — not just the borrower's personal finances. Net operating income (NOI) and debt service coverage ratio (DSCR) are primary underwriting metrics.
Commercial loans involve more parties, longer timelines, more detailed documentation, and more negotiation than residential mortgages. Understanding the process before entering it is essential.
Community banks, regional banks, life companies, CMBS lenders, SBA lenders, and private lenders all participate in commercial real estate — with different programs, appetites, and underwriting standards. Matching the transaction to the right lender type is part of the advisory work.
Different commercial transactions call for different financing structures. We help clients identify the program that fits their property type, use, and timeline.
Traditional commercial mortgage financing for the acquisition of income-producing commercial property. Underwritten primarily on the property’s NOI and DSCR, with loan terms typically ranging from 5 to 25 years with amortization periods of 20–30 years. Balloon payments are common at the end of the fixed rate period.
SBA programs specifically designed for business owners acquiring commercial real estate for their own business operations. SBA 504 offers lower down payment requirements (as low as 10%) for owner-occupied commercial property. The 51% owner-occupancy requirement must be met and maintained to access SBA commercial programs.
Rate-and-term refinancing or cash-out refinancing of an existing commercial real estate position. Lenders underwrite current occupancy, in-place income, and debt service coverage rather than projections. Seasoning requirements (typically 12–24 months) apply to cash-out refinances, and prepayment penalties on the existing loan are an important factor in the refinance decision.
Short-term financing (typically 12–36 months) designed to bridge the gap between acquisition or value-add repositioning and permanent financing. Common for properties that don’t yet meet stabilized occupancy or income requirements for conventional commercial lending. Higher cost than permanent financing — intended as a transitional tool, not a long-term position.
Financing for properties combining commercial and residential use — typically ground-floor retail or office with residential units above. Underwriting blends residential and commercial income analysis. The predominant use (commercial vs. residential by square footage or income) often determines which loan products and lender types apply.
Commercial real estate underwriting is fundamentally a financial analysis of the property’s income-generating capacity relative to the loan’s cost. These four metrics are the primary language lenders use — and the framework through which your transaction will be evaluated.
Understanding them before you sit across from a lender is part of how we help clients enter conversations more effectively.
Net Operating Income divided by annual debt service. A DSCR of 1.25x means the property generates 25% more income than the loan’s annual payment. Most conventional commercial lenders require 1.20–1.30x DSCR at minimum — below this threshold, the loan is likely to be declined regardless of other factors.
Gross rental income minus operating expenses (property management, insurance, taxes, maintenance, reserves) — before debt service. This is the foundational figure for all commercial income analysis. How NOI is calculated — and whether it is based on in-place rents or projected rents — significantly affects underwriting outcomes.
The loan amount divided by the appraised value of the property. Commercial lenders typically lend at 65–80% LTV, depending on property type, use, and borrower profile. Higher LTV means less equity required — but also less buffer in the lender’s risk position, which tends to mean stricter DSCR requirements.
The percentage of leasable space currently generating rent. Lenders generally require a minimum stabilized occupancy (commonly 85–90%) to underwrite on in-place income rather than projected income. Properties below this threshold may require bridge financing until stabilization, then transition to permanent commercial financing.
Commercial real estate financing follows a structured sequence. Our role is to ensure our clients understand the process, are positioned correctly at each stage, and are not surprised by lender requirements they could have anticipated.
Reviewing the property, its income profile, occupancy, lease structure, and the borrower’s financial position — the picture that will be presented to lenders in underwriting.
A candid early assessment of whether a deal is lendable as-structured saves significant time and money compared to discovering that in underwriting.
Matching the transaction to the appropriate loan program — conventional commercial, SBA, bridge, CMBS, or other — based on property type, occupancy, income profile, and the borrower’s objectives.
The right program varies significantly by transaction type. An owner-occupied acquisition and an investor acquisition of the same building may use entirely different financing structures.
Organizing the documentation lenders require — operating statements, rent rolls, lease agreements, property financials, borrower tax returns, entity documents, and the property summary — into a presentation that supports a clean underwriting process.
Commercial loan packages are substantially more complex than residential applications. The quality of the initial package often determines the pace of the entire process.
Supporting the client through the lender review process — helping interpret term sheets, understanding prepayment penalties and recourse provisions, and ensuring the client knows exactly what commitment they are making before signing.
Commercial loan terms can carry long-term consequences. Understanding what you are agreeing to — including balloon provisions, covenant requirements, and personal guarantee scope — matters as much as the rate.
Ground-up construction financing, spec home builder lines, and construction-to-permanent loans from site to certificate of occupancy.
DSCR loans, portfolio financing, fix-and-flip bridge loans, and investment property strategies for residential real estate investors.
SBA, term, lines of credit, equipment, and working capital financing for operating businesses seeking growth or stabilization capital.
Whether you’re acquiring, refinancing, or evaluating options — start with a conversation. We’ll give you an honest picture of where your transaction stands and what it will take to move forward.
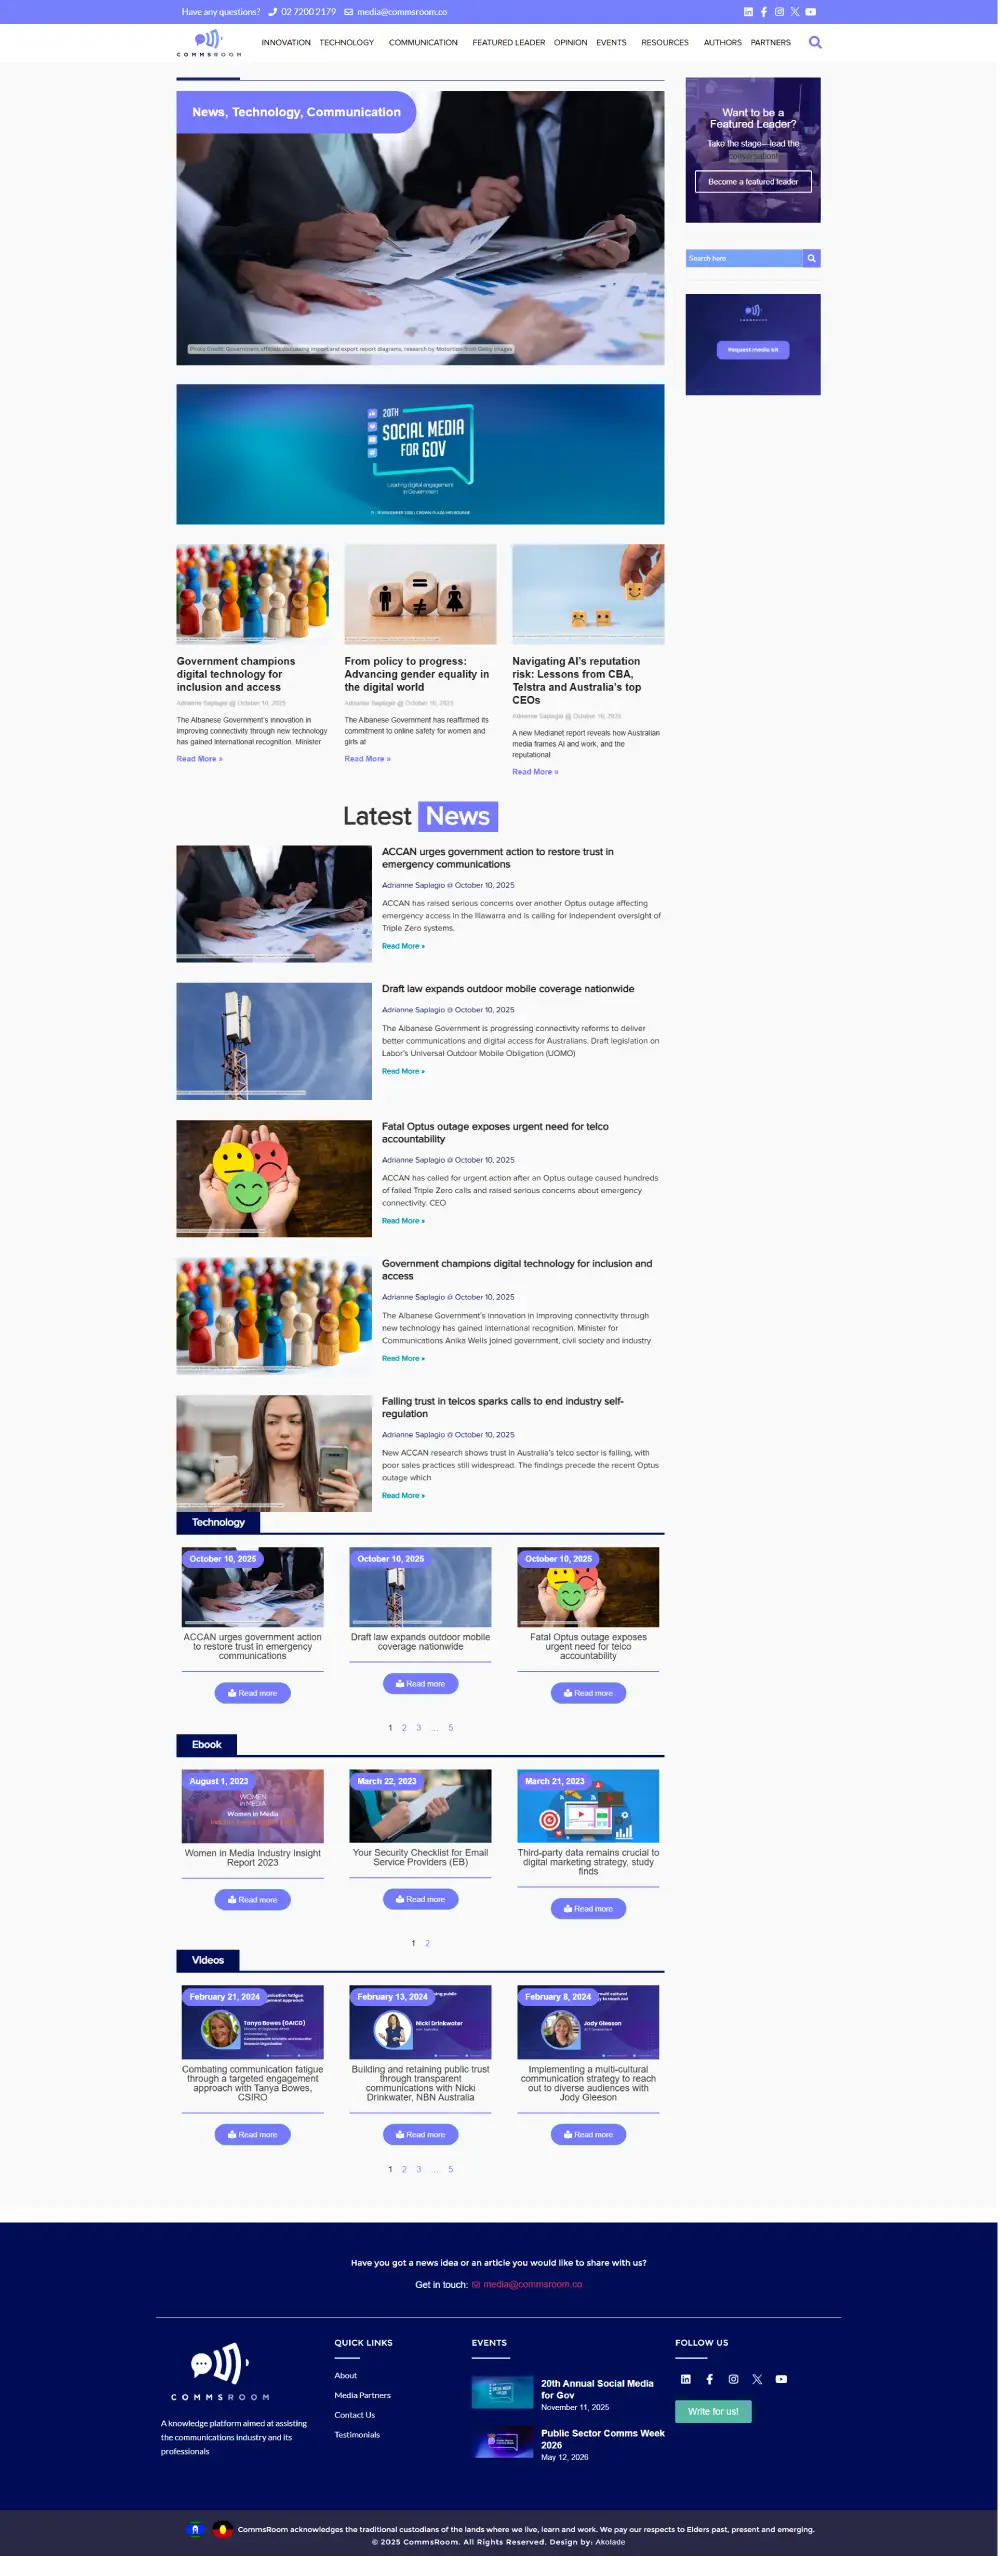
Comms Room, a leading communications newsletter website, wanted a modernized platform with a custom post type (CPT) setup to manage their daily articles and categorized content efficiently.
We developed a fully dynamic, user-friendly website that automates content organization, enhances navigation between topics, and supports high-volume publishing. The result is a sleek, modern platform that streamlines content management while elevating the reader experience — keeping Comms Room’s news delivery fast, engaging, and future-ready.