DSCR loans, portfolio financing, fix-and-flip bridge, and multi-family investment strategies — for investors who are building a portfolio, not buying a home. The right loan structure depends on your property type, timeline, and investment approach.
When you’re buying a property you won’t live in — whether it’s a rental, a flip, or a portfolio addition — lenders evaluate the transaction differently. The underwriting framework, loan products available, and qualification criteria all shift when the property is classified as an investment asset. We help real estate investors understand which financing structures apply to their specific situation, what qualifications are required, and how to approach the lender conversation in a way that reflects their investment strategy clearly and accurately.
Investment properties typically require 15–25% down for conventional financing — compared to 3–20% for primary residences. This reflects the lender's higher perceived risk on non-owner-occupied properties.
DSCR loans — Debt Service Coverage Ratio loans — qualify investors based on the property's rental income relative to the loan payment, rather than the investor's personal income. This changes the qualification calculus significantly for investors with complex tax returns.
Fannie Mae conforming loans cap the number of financed investment properties you can hold (currently 10 per borrower). Once you're beyond those limits, portfolio lending and alternative structures become relevant.
A buy-and-hold rental and a fix-and-flip require fundamentally different financing. DSCR and conventional investment loans suit long-term holds; bridge and hard money are short-term instruments designed for acquisition-to-rehab-to-sale or refinance cycles.
DSCR — Debt Service Coverage Ratio — loans have become one of the most important tools for real estate investors over the past several years. They qualify investors based on the property’s rental income rather than the borrower’s personal income. Understanding how they work is essential for any investor building a rental portfolio.
Debt Service Coverage Ratio is the ratio of a property’s monthly gross rental income to its monthly PITIA (Principal, Interest, Taxes, Insurance, and Association dues). A DSCR of 1.0 means the property’s rent exactly covers the loan payment. Most lenders require 1.0–1.25x DSCR at minimum; a higher ratio gives the borrower more pricing flexibility.
DSCR loans are most valuable for investors with complex tax returns — self-employed borrowers, investors who write off significant expenses, or those with many existing financed properties. Since personal income is not part of the equation, these borrowers can continue to qualify even when their W-2 income or adjusted gross income doesn’t reflect their actual financial strength.
For existing rentals, lenders use actual lease agreements or a CPA-prepared rental schedule. For vacant properties or new purchases, lenders use a third-party market rent survey (form 1007 or 1025) completed by a licensed appraiser — which estimates what the property could rent for in the current market.
DSCR loans typically carry slightly higher rates than conventional investment property loans and require stronger DSCR ratios on the specific property. They compensate for this with income-based qualification, no Fannie/Freddie property count limits, and faster processing timelines. For investors beyond 10 financed properties or with complex income situations, the tradeoffs are typically favorable.
Some DSCR lenders accept short-term rental (Airbnb/VRBO) income for qualification — typically documented through AirDNA data or a 12-month actual rental history. Other programs require that STR properties be underwritten using long-term market rents only. The approach varies significantly by lender and market, which is part of why program selection matters.
The most accessible entry point for real estate investors. SFRs and condos benefit from the widest lender selection — conventional, DSCR, and portfolio programs all apply. Easiest to finance and manage individually; at scale, investors typically migrate toward DSCR or portfolio lending.
DSCRConventionalPortfolioSTR Eligible
Duplexes, triplexes, and fourplexes still fall within residential financing guidelines — meaning conventional and DSCR programs apply. An FHA owner-occupant strategy is also available for primary residence purchase of 2–4 unit properties. Strong cash-flow profile relative to single-family at similar acquisition costs.
DSCRConventionalFHA Eligible2–4 Units
Once a property reaches 5 units, it crosses into commercial underwriting territory regardless of the borrower profile. Financing shifts to commercial multi-family programs — agency (Fannie/Freddie multifamily), bank portfolio, bridge, or CMBS — underwritten primarily on NOI, DSCR, and occupancy rather than personal income.
CommercialAgency MFPortfolioNOI-Based
Short-term acquisition and renovation financing for investors purchasing below-market properties, improving them, and selling. Financing is typically based on after-repair value (ARV) rather than purchase price. Bridge and hard money loans dominate this space — short terms (6–24 months), higher rates, rapid execution, and draw-based rehab funding. Exit is typically sale or refi into a DSCR hold loan.
Bridge / Hard MoneyARV-BasedDraw-Based6–24 Months
Investment property financing advisory moves through a clear sequence — from strategy alignment to program identification to lender navigation.
Understanding the investor’s current portfolio, investment strategy (buy-hold, flip, STR, multi-family), personal financial profile, and near-term acquisition pipeline — the full picture before identifying any financing structure.
Matching the investor and property type to the right financing structure — DSCR, conventional, portfolio, bridge, or multi-family commercial — based on their profile, goals, and the specific transaction.
Organizing the documentation package the lender will require — rental income documentation, property information, entity structure, existing portfolio schedules, and borrower financials — so the application process is clean and efficient.
Guiding the client through the lender evaluation process — interpreting rate and fee structures, understanding prepayment penalties (particularly on DSCR products), and ensuring the client understands what they are committing to before closing.
Advising on the financing progression as portfolios grow — when to move from conventional to DSCR, when portfolio lending becomes relevant, how to structure entities to support ongoing acquisition, and how financing strategy should evolve alongside the portfolio itself.
Connecting the financing strategy to the right ownership structure — LLC formation, single-member vs. multi-member entities, and series LLCs for multi-property portfolios. We work in concert with legal and tax advisors to ensure the financing and ownership approaches are aligned.

Ground-up construction financing, spec home builder lines, and construction-to-permanent loans for developers and builders.
Commercial real estate mortgages, owner-occupied commercial financing, SBA programs, and commercial refinancing.
Entity selection, LLC formation, and ownership structure for real estate investors — before you pursue financing.
Whether you’re buying your first rental property or adding to an existing portfolio — start with a conversation. We’ll help you understand which financing structure fits your situation and what it will take to move forward.
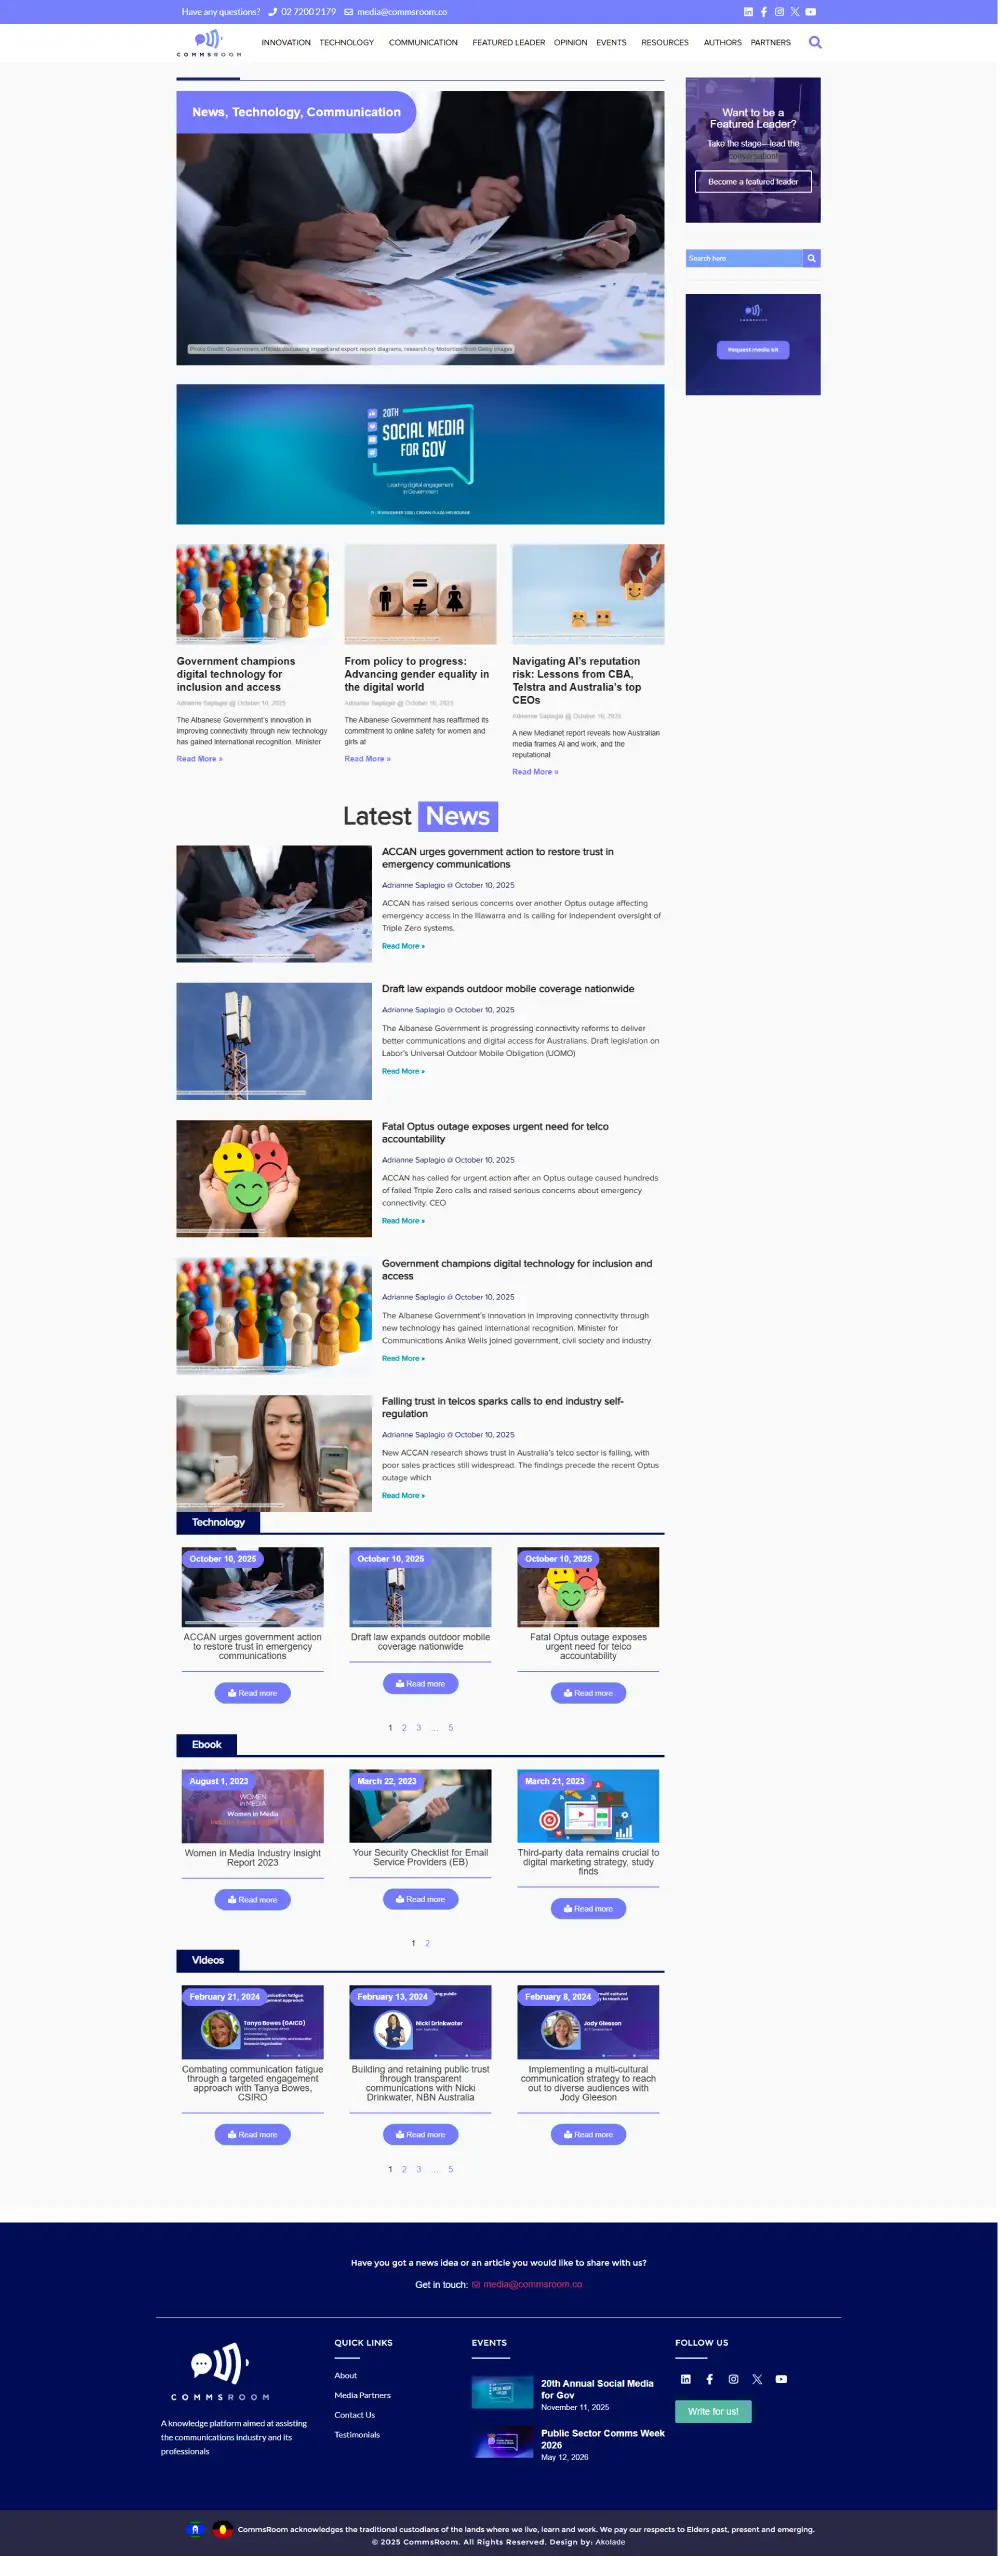
Comms Room, a leading communications newsletter website, wanted a modernized platform with a custom post type (CPT) setup to manage their daily articles and categorized content efficiently.
We developed a fully dynamic, user-friendly website that automates content organization, enhances navigation between topics, and supports high-volume publishing. The result is a sleek, modern platform that streamlines content management while elevating the reader experience — keeping Comms Room’s news delivery fast, engaging, and future-ready.